Selling a Car with Finance in Australia: The Complete 2026 Guide
Owing money on your car doesn’t trap you in the driver’s seat. Many Australian motorists worry that selling an encumbered vehicle breaches their finance contract, or that prospective buyers will walk away the moment a financial interest appears on a PPSR check. Between confusing lender calculations and strict transport authority rules, the handover process can easily feel overwhelming. However, selling a car with finance Australia wide is entirely legal, routine, and manageable once you understand how the payout logistics work.
An active loan doesn’t prevent a successful sale; you simply need a structured method to settle the balance. In this guide, you will discover how to request an official lender payout figure, calculate whether your car holds positive or negative equity, and clear your debt safely. We break down the fastest handover options available, showing you how to maximise your vehicle’s sale value and transfer registration with complete peace of mind.
Key Takeaways
- Selling an encumbered vehicle is completely legal across Australia once the lender’s registered security interest is settled and removed from the PPSR.
- An official financier payout figure accounts for daily interest and termination fees, revealing whether your vehicle holds positive or negative equity.
- Explore the three practical methods for selling a car with finance Australia wide, weighing upfront self-settlement against direct buyer handovers.
- Follow a systematic five-step roadmap to align personal lender payments with state transport registration transfers cleanly.
- Connecting directly with vetted professional used car buyers ensures the payout is handled on your behalf, removing private buyer hesitation entirely.
Can You Legally Sell a Financed Car in Australia?
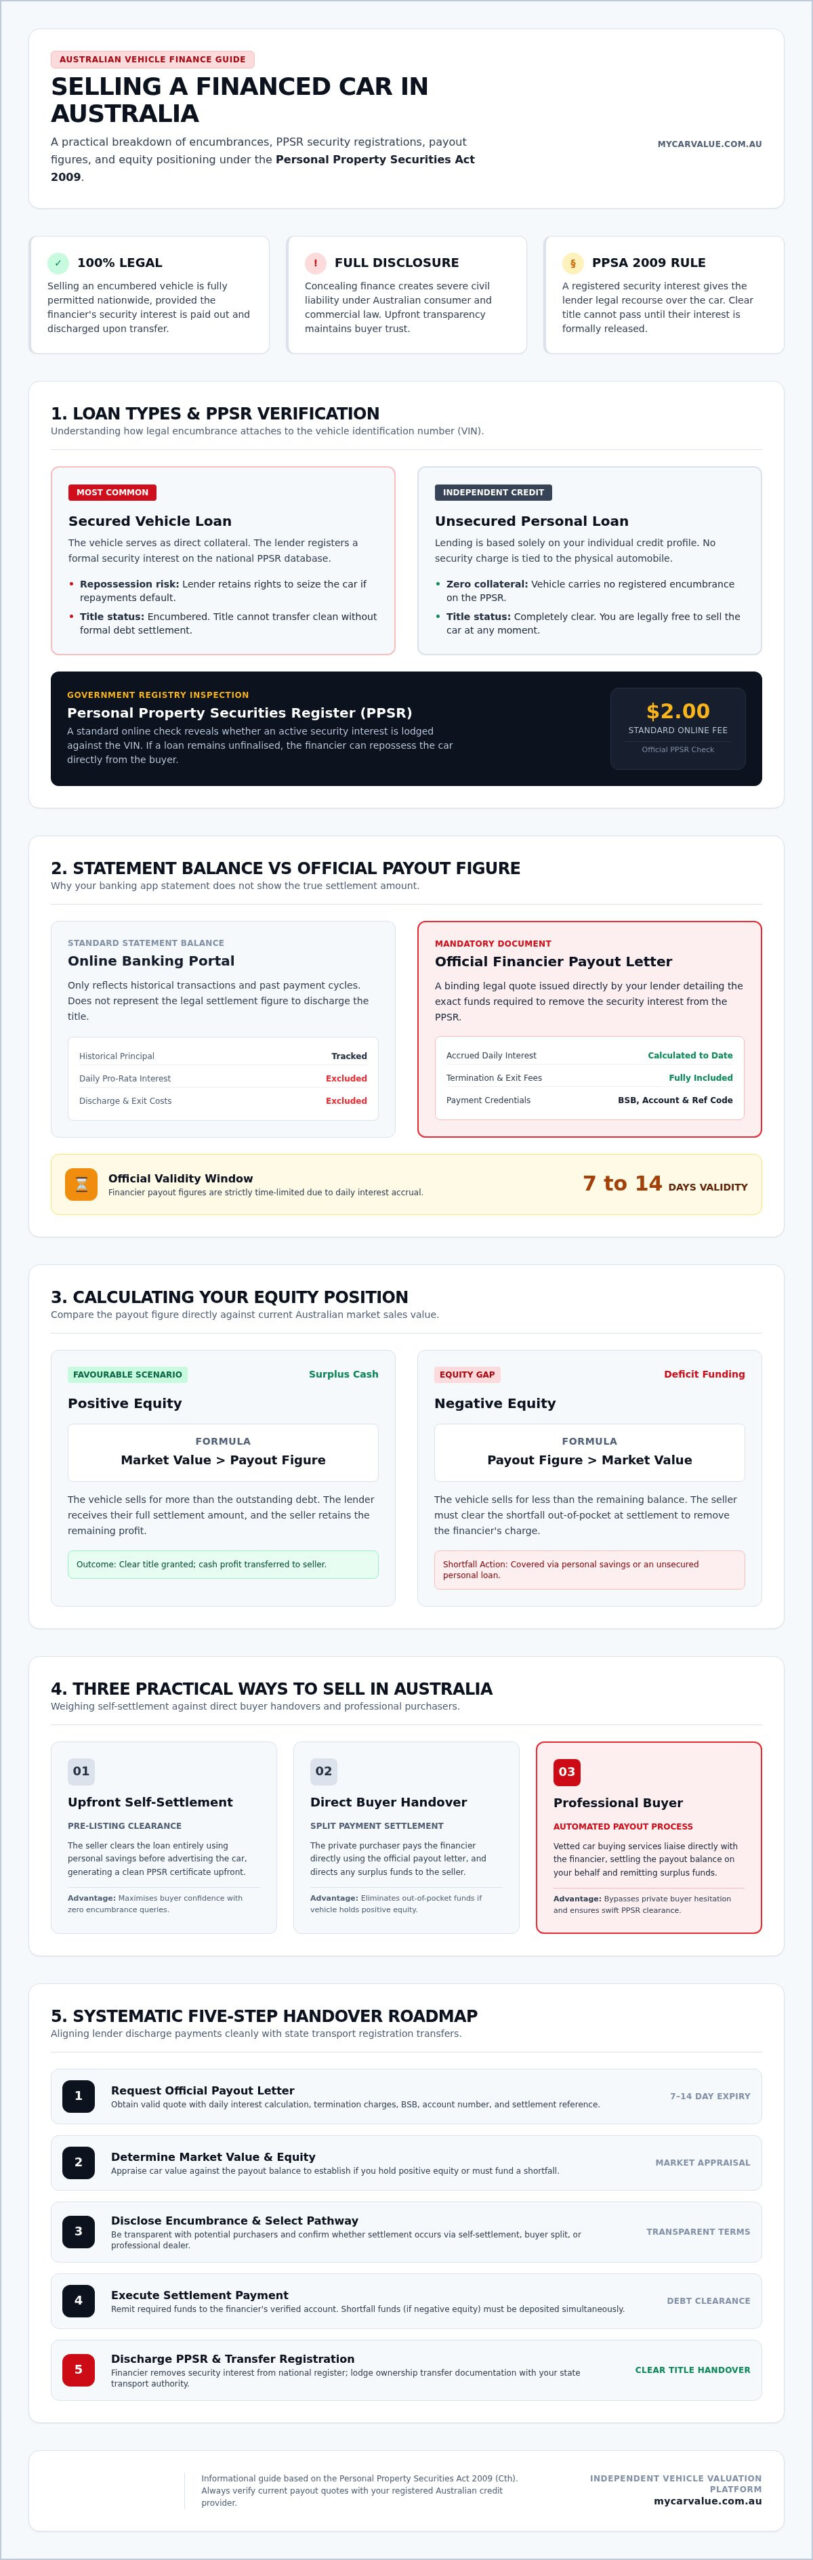
Yes, you can. Selling an encumbered vehicle is completely legal across Australia, provided the debt is settled in full during or immediately before the transfer of ownership. Under the Personal Property Securities Act 2009, an encumbrance is a registered legal security interest that grants a financier legal recourse against personal property if the borrower defaults on their loan obligations. Until your financier formally receives their settlement payment, they hold a legal claim over the car, meaning you cannot transfer a clear, unencumbered title without their involvement.
Transparency is critical when selling a car with finance Australia wide. Hiding an existing loan from a private purchaser creates immediate legal exposure, potentially triggering civil claims for deceptive conduct. Disclosing the debt upfront protects you from disputes and maintains buyer trust throughout the negotiation.
Understanding Secured Car Loans and Encumbrance
Most vehicle finance in Australia takes the form of a secured loan. In this arrangement, the lender uses the car itself as collateral against potential default, registering this interest on the national asset database. If you miss repayments, the lender retains the legal authority to repossess and liquidate the vehicle to recover their funds.
Unsecured personal loans operate quite differently:
- No collateral attached: The lender lends based on your credit profile, meaning the car carries no legal encumbrance.
- Clear title: You can sell the vehicle freely at any moment, as the debt remains tied solely to you as an individual, not the car.
The Role of the PPSR in Australian Car Sales
Informed buyers always protect themselves before handing over funds. For a standard fee of $2, anyone can run an online check via the Personal Property Securities Register (PPSR) to reveal whether an Australian financial institution holds an active interest in the vehicle identification number (VIN).
A clean PPSR certificate confirms clear title. If a seller transfers a vehicle without discharging the loan, that security interest remains attached to the car. As a result, the financier retains the right to repossess the vehicle from the new owner, creating serious liability for the seller. Settle the loan correctly, and the financier will remove their listing from the register, finalising a clean legal handover.
Calculating Your Position: Payout Figure vs Market Value
Checking your banking app doesn’t show what you actually owe to close out an auto loan. The standard balance displayed on your regular statement merely tracks past transactions. In contrast, an official payout figure includes accrued daily interest right up to the settlement date, alongside any administrative termination fees or early exit costs. Knowing this exact figure is the essential first step when selling a car with finance Australia wide, as it reveals your actual financial standing.
Once you have this number, compare it directly against the current market price of your vehicle. Using a vehicle market value calculator gives you a grounded appraisal based on current Australian sales data. This comparison establishes your equity position, determining whether you walk away with extra cash or need to contribute funds to finalise the transfer.
How to Request an Official Payout Letter
Ring your financier or log into your online portal to request a formal payout quote. Lenders provide an official document detailing the precise amount needed to release their security interest on the official government register. These statements remain valid for a limited window, typically 7 to 14 days. The document sets out the lender’s BSB, account number, and your specific settlement reference code so funds land in the right place without delay.
Managing Positive Equity versus Negative Equity
Your equity position dictates your entire sales strategy:
- Positive Equity: The car’s market value exceeds your payout figure. If your vehicle sells for more than the debt, your lender receives their settlement amount, and you pocket the remaining profit.
- Negative Equity: The payout balance is higher than the vehicle’s market worth. If a car fetches less than the outstanding loan, an equity gap occurs.
Negative equity demands decisive action. You must clear the shortfall out of your own pocket to release the financier’s charge. You can pay this difference using personal savings at settlement, or arrange an unsecured personal loan to bridge the remaining deficit. Getting a realistic estimate upfront prevents unexpected shortfalls on handover day, making it easy to value my car accurately before committing to a deal.
Three Ways to Sell a Vehicle Under Finance in Australia
You have three distinct avenues for selling a car with finance Australia wide. The right path depends on whether you prioritise obtaining maximum gross return, minimising administrative paperwork, or completing the transaction quickly. If you hold sufficient savings, paying out the contract before advertising eliminates encumbrance entirely. However, most motorists rely on the sale proceeds to clear the debt. Weighing your broader sell my car options helps determine which strategy matches your schedule and comfort level.
Selling Privately with an Existing Car Loan
Listing on private classifieds can yield a competitive sale price, but an active loan introduces significant friction. Everyday buyers get nervous when a PPSR check flags an encumbered vehicle. Managing the settlement requires split payments: the buyer must transfer funds directly to your financier using your payout letter details, then transfer any remaining balance to your personal account. Independent consumer guides outlining selling a car with an outstanding loan highlight that many private shoppers simply walk away rather than navigate multi-party bank transfers.
Working with Professional Used Car Buyers
Engaging professional buyers cuts out private purchaser hesitation. Instead of coordinating complex communications between a cautious individual and your lender, professional used car buyers settle the loan balance directly with the financier on your behalf. They verify the official payout statement, transfer the exact balance to clear the security interest, and deposit any surplus positive equity directly into your account. This route eliminates administrative disputes, test-drive risks, and payment delays.
Dealership Trade-Ins and Valuation Differences
Dealerships routinely process loan payouts, often rolling residual balances into a subsequent finance contract. While convenient, trade-in valuations frequently sit well below independent market worth. Dealerships factor substantial retail margins into their trade appraisals. Bundling your disposal with a replacement vehicle purchase also obscures the real numbers, giving you less bargaining leverage than handling your sale as an independent transaction.
Step-by-Step Guide to Settling Finance and Transferring Ownership
Completing a vehicle sale while carrying an active loan demands an orderly workflow. Missing a single step can delay settlement or cause unnecessary friction with registration authorities. Following a systematic roadmap ensures every party fulfills their legal obligations without ambiguity.
Assemble your documentation before beginning negotiations. You will need your current registration certificate, a complete logbook service history, and an official bill of sale. Your bill of sale should document the full purchase amount, vehicle identification details, and the precise division of funds between your financier and your personal account. Never release the keys or complete registration transfer forms until you verify cleared funds.
Steps 1 to 3: Preparation, Pricing, and Payout Quotes
Start by securing an updated payout statement from your lending institution, noting the settlement expiry date and daily interest charges. Next, establish a realistic valuation benchmark so you know where your equity stands before agreeing to terms. Finally, disclose the encumbrance directly to your buyer. Providing a clear copy of your lender payout letter builds immediate confidence and establishes clear payment expectations.
Steps 4 to 5: Fund Disbursement and Registration Transfer
Executing the final handover correctly protects both parties:
- Direct lender settlement: The buyer pays the lender directly using the payment slip on the payout letter, transferring any remaining balance to your personal account.
- PPSR discharge timeline: Once the lender receives full settlement, they initiate the release of their security interest. Financiers typically take two to five business days to update the PPSR database and remove the registered encumbrance.
- Ownership lodgement: Complete the transfer of registration via your state transport authority’s digital portal or paper transfer form, providing a signed receipt to the buyer.
- Final verification: Run an independent PPSR search several business days post-settlement to confirm the vehicle now carries a clean, unencumbered status.
Understanding these steps makes selling a car with finance Australia wide a transparent and predictable transaction from initial valuation to ownership handover.
How My Car Value Simplifies Selling a Financed Car
Managing an encumbered vehicle sale on your own often involves stressful back-and-forth negotiations with sceptical private buyers. My Car Value simplifies this process by matching sellers directly with vetted, professional used car buyers nationwide. Instead of paying classified listing fees or fielding calls from strangers who don’t understand financing, you gain transparent, data-driven market insights before making any commitments. Professional automotive buyers handle the liaison with your lender, transferring the payout directly to clear the registered debt. This modern platform delivers a fast, transparent, and completely dependable path to handing over your keys.
Eliminating the Stress of Private Encumbrance Enquiries
Selling privately often forces you to justify your loan balance to inexperienced buyers who mistake a routine security interest for an insurmountable risk. Qualified buyer networks deal with Australian financing mechanics every day, making the payout exchange straightforward and routine.
Connecting with professional buyers removes several persistent headaches:
- Zero payout hesitation: Professional purchasers work directly with your lender’s official settlement letter, completely eliminating awkward financial discussions.
- Enhanced personal safety: Avoid risky payment schemes, uninsured test drives, and cancelled weekend appointments at your home.
- Guaranteed debt clearance: Commercial buyers settle the financier’s account directly, ensuring the lender discharges their registered interest without delay.
Streamlined National Matching for Faster Vehicle Sales
Achieving a fair return means tapping into real-time demand across the country. My Car Value connects your vehicle with professional buyers actively sourcing quality stock, securing competitive market appraisals without the steep trade-in markdowns common at traditional dealerships. The transition from initial assessment to final fund disbursement remains fully transparent. When selling a car with finance Australia wide, using a dedicated buyer network gives you complete control over your loan exit without the administrative burden.
Take the Next Step Toward a Clean Vehicle Sale
Managing an outstanding car loan doesn’t need to delay your plans or complicate your handover. Once you secure an official payout letter and calculate your equity position, clearing the debt becomes a straightforward, predictable transaction. Selling a car with finance Australia wide is an everyday occurrence, and choosing the right sales pathway eliminates the hesitation common in private classified sales.
Obtaining an independent appraisal based on current market conditions ensures you capture your vehicle’s real-world value. A vetted national network of professional used car buyers can manage the entire lender liaison directly, transferring settlement funds to release the encumbrance while depositing any positive equity straight into your account.
Say goodbye to finance confusion, clear your debt smoothly, and move on to your next vehicle with complete peace of mind.
Frequently Asked Questions
Can I sell my car privately if it is still under finance?
Yes, you can legally sell privately, but you must coordinate settlement directly with your financier. Inform the prospective buyer immediately about the registered encumbrance. The buyer must pay the lender’s payout balance directly to release the security interest, forwarding any extra funds to you. Transparency is essential when selling a car with finance Australia wide to prevent delays, broken agreements, or legal disputes over unreleased title.
What is an official car loan payout letter and how long is it valid?
An official payout letter is a formal statement issued by your lender detailing the exact settlement amount required to clear your debt. This figure incorporates your principal loan balance, early termination fees, and daily calculated interest. Financiers typically make these statements valid for 7 to 14 days. If the settlement does not finalise within that window, you must request a recalculated statement reflecting accrued interest before proceeding.
What happens if my car is worth less than what I owe on my loan?
This situation is known as negative equity, and you must cover the financial gap yourself. Because the vehicle’s market value won’t fully clear the debt, your lender won’t release their security interest until the remaining balance is paid. You must contribute the difference using personal savings or an alternate personal loan at the point of handover. Securing a grounded valuation early prevents unexpected shortfalls when finalising the deal.
How long does it take for a lender to remove encumbrance from the PPSR?
Most Australian financiers remove their registered security interest within two to five business days after receiving cleared funds. While the bank clears the loan internally almost immediately, updating the government asset register requires administrative processing. Once the funds land, ask your lender for an official letter of non-interest. This document serves as proof of debt discharge for the buyer while the online register updates.
Do professional car buyers pay out my lender directly when purchasing my vehicle?
Yes, professional used car buyers routinely settle existing finance balances directly with your lender. You simply provide your current payout letter, and the buyer transfers the specified debt balance straight to the financier. If your vehicle sells for more than the debt, the buyer deposits the remaining positive equity into your account. This approach bypasses the hesitation and manual coordination often encountered with private classified buyers.
Can I sell a car with an unsecured personal loan without PPSR issues?
Yes, because an unsecured personal loan does not attach collateral to the vehicle itself. The financier holds no registered security interest on the national asset register, meaning the car carries a clear title. You can sell the car at any time without involving the lender in the transfer. However, you remain legally responsible for continuing your regular loan repayments until the personal debt is completely extinguished.
What documents do I need to sell an encumbered vehicle in Australia?
You need your official lender payout letter with current validity dates, current vehicle registration papers, complete service logbooks, and valid photo identification. Prepare a formal bill of sale detailing the agreed purchase price, the split payment to your financier, and any balance paid to you. These records ensure a seamless registration transfer and prove compliance when selling a car with finance Australia wide.